
In short: gift tax in Valencia (the Comunitat Valenciana) for residents: when your parents give you money, the tax can come to €0. For this tax, residence counts where you spent the most days in the last 5 years. First a reduction of €100,000 comes off, and 99 % of the remaining tax is waived. So €15,000 from your mother pays nothing, on three conditions: a public document, a justified origin of the money and the Modelo 651 within one month. All of this applies only to residents of the Comunitat Valenciana: if you reside in another region, the rules are different, so check yours.
In person or by representative? The Modelo 651 is filed online with an electronic certificate at the ATV (Agència Tributària Valenciana), or at an ATV office with an appointment. A representative can also file it online if you give them authority in the ATV representatives register (with a digital certificate); the donations 651 is among the procedures that can be delegated. The notary is a separate step: if the person giving you the money lives outside Spain, ask the notary how they can sign before sending anything.
Who pays and which rules apply
The person who receives the money pays, the donee (art. 5 of Law 29/1987 on Inheritance and Gift Tax, ISD). If you reside in Spain, you are taxed on what you receive even if it comes from abroad (art. 6 of the same law). For money, the rules of the autonomous community where you have your habitual residence on the day of the gift apply. Where the donor lives does not change this (art. 32 of Law 22/2009).
For this tax, your habitual residence is the community where you spent the most days in the previous 5 years (art. 28 of Law 22/2009). Temporary absences count as days in that community and, unless proven otherwise, you are considered to be where your habitual home is. This is not the 183-day rule of the Renta: that one is in tax residence and the 183 days. In practice, the padrón can serve as an indication, though it is not a rule.
How much you pay in the Comunitat Valenciana
The tax depends on the family relationship between giver and receiver (the groups in art. 20 of Law 29/1987).
- Children, parents, spouse, grandchildren and grandparents (groups I and II). Two advantages add up. First, a reduction of €100,000 on what you receive (art. 10 bis of Law 13/1997 of the Comunitat Valenciana). For children and grandchildren under 21 it is higher: €100,000 plus €8,000 for each year they are short of 21, up to €156,000. Second, a 99 % relief on the tax that remains (art. 12 bis).
- Siblings, uncles, aunts, nephews and nieces (group III, blood relatives of second and third degree). The €100,000 reduction is not provided for this group. The relief is 25 % of the tax. From 1 June 2027 it is 50 % (art. 12 bis.2, as changed by Law 5/2026). Group III relatives by marriage, for example parents-in-law, are not named in that relief.
- Other people (group IV: cousins, friends, acquaintances). No reduction and no relief. The full scale applies, from 7.65 % to 34 % (art. 11), multiplied by a coefficient based on your prior wealth (for group IV, from 2.0 to 2.4; art. 12). With €15,000 and prior wealth of up to €390,657.87 the tax is about €2,414.
The €100,000 limit counts all gifts from the same donor in the previous 5 years. Examples, with no other gifts from the same donor in those 5 years:
- €15,000 from your mother: after the reduction the base is 0 and the tax is €0.
- €100,000: the same, €0.
- €150,000 to a child aged 21 or over, with prior wealth of up to €390,657.87: the reduction leaves a base of €50,000. With the scale in art. 11 the tax comes to about €4,976 and, with the 99 % relief, about €50. This is our indicative calculation: the ATV program gives the exact figure when you file.
The three conditions for the 99 %
The reduction and the relief do not apply if the public document or the justification of the origin of the money is missing. The Modelo 651 must be filed within one month; if you are late, see below.
- Public document. The gift must be recorded in a public document, in practice a deed before a notary, or formalised that way within the one-month deadline for filing the 651 (arts. 10 bis and 12 bis.4). Since 11 August 2026 (Law 5/2026) there is an exception for money. If what is given does not exceed €4,000, adding up the deliveries from the same donor to the same donee in the previous 3 years, a document with a qualified electronic signature (the kind defined by the European eIDAS regulation) can replace the notary. Condition: the validity of the gift must not require another form.
- Origin of the money. With money, both benefits apply only if the origin of the funds is duly justified and the gift document states that origin and identifies the means by which the money is delivered, for example a bank transfer. This also applies to gifts of up to €4,000. The law does not list the proof; in practice statements, income certificates or a sale contract of the donor are used (usual examples; there is no official list).
- Declare the gift on the Modelo 651 within one month. It is filed within one month of the day of the gift (art. 12 ter of Law 13/1997). It is not 30 working days: the Comunitat Valenciana has its own deadline, and for gifts there is no extension (ATV). If you already have the money and there is no document yet, check with the notary or the ATV from which day the month counts.
If you file late. If you file on your own before the tax office contacts you and the 651 includes everything you received, you do not lose the relief (art. 12 bis.3), as long as the gift was already recorded in a public document (or in a document with a qualified electronic signature up to €4,000) within the month. You pay surcharges (art. 27 LGT, the General Tax Law): 1 % plus 1 % for each full month of delay and, after 12 months, 15 % plus late-payment interest. If the result is €0 to pay there is no surcharge, but there may be a fixed fine (art. 198 LGT). If a notice reaches you first, the relief does not cover what was not declared. More on surcharges and fines: tax return for foreign residents.
Money coming from Ukraine or another country
- You pay the tax in Spain if you reside here, under the rules of your community (art. 6 of Law 29/1987 and art. 32 of Law 22/2009).
- Use a bank transfer to your account: it leaves a trail and fits the means of delivery that must appear in the document. The bank may ask you to explain where the money comes from. This is a usual bank practice and this law does not regulate it; have the same proof from point 2 ready.
- Monthly help to live on (alimentos). If your family sends you money every month for your expenses, it may be seen as family support and not a gift. In our July 2026 review we did not find a DGT ruling that settles this for adults: it is a grey area. Ask an adviser and keep proof of why you need it.
- Fundraisers or volunteers' money to your personal card. Each person who sends you money can count as a donor, and without a family tie that is group IV, with no benefits. This is also a grey area: ask an adviser first.
- Renta. Income subject to the ISD is not subject to IRPF (art. 6.4 of Law 35/2006), so the gift is not Renta income. You declare it on the Modelo 651.
When this does not apply
- You are not a resident of the Comunitat Valenciana under the 5-year rule: your own community's rules apply, with their own reductions, reliefs and deadlines. If you do not reside in Spain, this card does not apply: ask an adviser.
- A gift of real estate: the applicable community is where the property is (art. 32 of Law 22/2009) and there are other conditions. This card covers money only.
- Money from friends, cousins or other people without a close family tie: group IV, no benefits (see above).
- Loans and payments for work or a sale: these are not gifts and this card does not cover them.
Documents
- Identification details of the giver and the receiver: NIF or NIE, name, address and date of birth. If the giver has no NIF, ask the ATV which detail to give. If you do not have a NIE: how to apply for the NIE.
- The gift document: a deed before a notary or, up to €4,000, a document with a qualified electronic signature. It must state the origin of the money and the means of delivery. If it is a notarial deed, the ATV says it no longer needs to be provided when you file; it must still exist and you should keep it.
- Proof of the bank transfer.
- Proof of the origin of the donor's money, depending on the case (usual examples, no official list): statements, an income certificate, a sale contract.
- Family book or birth certificate proving the family tie, if you claim the reduction or relief. If it comes from another country, ask the ATV whether it needs a translation or legalisation.
- An electronic certificate to file online: Cl@ve and electronic certificate.
Indicative list: the ATV also asks for other data depending on the case; check it on its donations page.
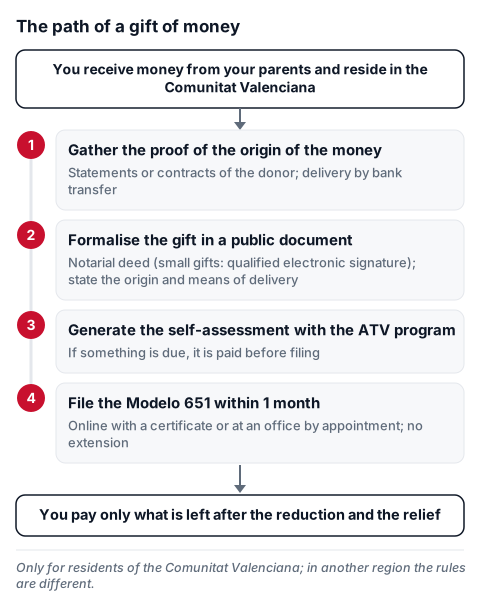
Steps
- Check that you are a resident of the Comunitat Valenciana (more days here in the previous 5 years) and which family group you belong to.
- Before the money is sent, prepare the proof of its origin and agree that it will be delivered by bank transfer to your account.
- Formalise the gift in a public document before a notary within the month or, up to €4,000, in a document with a qualified electronic signature. The origin of the money and the means of delivery must appear.
- Generate the self-assessment with the ATV help program: it is the tax calculation of the Modelo 651.
- If something is due, pay before filing (the ATV works in this order: generate the self-assessment, pay, file), through the ATV payment gateway, a collaborating bank or Correos. If you pay in person, the system takes at least 2 days to recognise the payment: do not leave it for the last day of the month. File even if the tax comes out low or at €0: the relief covers only what you declare (art. 12 bis.3).
- File the Modelo 651 within one month, online with an electronic certificate or at an office with an appointment. There is no extension.
- Keep the filing receipt, the deed and the proof of the origin of the money for at least 4 years (limitation period, art. 66 LGT).
Official source: Law 13/1997, arts. 10 bis, 12 bis and 12 ter, BOE and ATV, I want to declare a gift.
Informational only; check the official source and a professional for your specific case. Consolidated text of Law 13/1997 checked on 1 October 2026.
