
Update 2026-10-08: Royal Decree-law 29/2026 of 6.10.2026 adds Article 68.6 of the IRPF law: a deduction of 10% of what you pay in rent for your main home, with a taxable base below €33,007.20 and up to €1,163 a year; it also requires that neither you nor your family unit has another home within 50 km of the rented one for at least half a year. It has been in force since 8.10.2026, but Congress must validate or repeal it within 30 days of its promulgation on 6.10.2026 (art. 86.2 of the Spanish Constitution), as it did on 2.10.2026 with RDL 26/2026 and 27/2026. The text we read does not say which return it applies to; if you need to file a tax return in Spain, do not count on it yet. More: news item. If you acted under earlier rules, talk to a professional.
In short: do you need to file a tax return in Spain as a foreign resident? Yes, if you pass an income limit. The general limit is €22,000 a year of salary or pension from a single payer. It drops to €15,876 if you are paid by more than one payer (the second and later ones above €1,500). It also drops if you are paid by someone who does not withhold IRPF (the income tax) in Spain, such as a foreign employer or a pension from abroad. Below the limit you can still file, and sometimes you get money back. Today (October 2026) no filing campaign is open: the Renta 2025 closed on 30 June 2026; the next one, on 2026 income, is filed in 2027 (dates to be announced).
In person or by representative? You do it online, without going to an office: Renta WEB with Cl@ve, an electronic certificate or a reference number. A voluntary representative with powers (an apoderado) or a duly authorised social collaborator can also file it for you online, using their own electronic certificate. You can file by phone or at an office with an appointment too, but those two routes are not allowed if the result is to pay and you do not direct-debit the payment. More: filing deadline and methods and the AEAT website (the Tax Agency).
Who files the Renta? Tax residents of Spain. In general, you are one if you spend more than 183 days of the calendar year in the country, or if your main activities or economic interests are here (art. 9 LIRPF, the personal income tax law). How days are counted: tax residence and the 183 days. A resident is taxed on all income, whether it comes from Spain or from another country. If you are not a tax resident you pay IRNR (non-resident income tax) on other forms, for example Modelo 210 for a property: buying property as a foreigner.
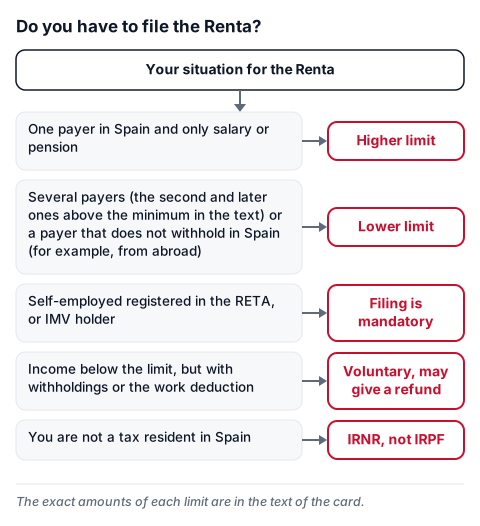
Income limits (art. 96 LIRPF): you do not have to file if all your income for the year comes from these sources and stays within these limits. They are the same for Renta 2025 and, according to the current BOE text on 1 October 2026, for Renta 2026 (the one filed in 2027).
- €22,000 a year of gross work income (salary or pension) from a single payer. Also if there are several payers, but what you receive from the second and the following ones adds up to €1,500 a year or less.
- €15,876 a year, instead of €22,000, in any of these cases:
- more than one payer, and the second and following ones add up to more than €1,500;
- a compensatory pension from a spouse or non-exempt maintenance payments;
- a payer with no obligation to withhold IRPF in Spain (for example, a foreign employer or a pension from abroad);
- withholding at a fixed rate.
- €1,600 a year combined from investment income (interest, dividends) and capital gains with withholding.
- €1,000 a year combined from imputed property income (a property you own and do not rent out), Treasury bills, subsidies for protected housing and other gains from public aid.
- €1,000 a year in total if you mix income from work, capital or a business activity with capital gains, and capital losses stay below €500.
These people always file, among others, whatever the amount:
- anyone registered as self-employed (RETA) at any time of the year;
- holders of the minimum living income (IMV) and the people in their household unit;
- anyone claiming the international double taxation deduction;
- anyone claiming reductions for contributions to pension plans and other social-security savings schemes.
If you are paid from abroad. A salary or pension from outside Spain falls under the rule of the payer who does not withhold IRPF when that payer does not operate in Spain. The AEAT itself explains it for pensions: a non-resident payer is not obliged to withhold as long as it does not operate in Spain. In that case your limit becomes €15,876 even with a single payer. If the payer abroad does operate in Spain, the rule may be different: check your case. With income from a business activity and no RETA registration, check your case too: the margin for not filing is €1,000 a year in total.
Below the limit you can still file. If you are not obliged, the AEAT lets you file to claim the refund you are entitled to, if any. It lets you recover tax withheld in excess. The deductions you are entitled to lower the tax and can increase the refund. The work-income deduction (additional provision 61 of the LIRPF) lowers your quota, meaning the tax you pay, by up to €340 for Renta 2025 and up to €590.89 for Renta 2026. For income of 2026 (Renta 2026, filed in 2027) the full amount is for gross work income of up to €17,094 a year; it falls gradually and reaches 0 at €20,048.45. It requires an employment or statutory relationship and other income, exempt income aside, of no more than €6,500.
You were not required to file, but tax was withheld
If in any year from 2022 to 2025 you stayed under the limit and did not file the Renta, the extra tax withheld stayed with the tax office. It is only refunded if you file that year's Renta. The general limit was €22,000 in all four years. The reduced one, for the €15,876 cases in the list above (for example, several payers or a payer that does not withhold in Spain), changed (art. 96 LIRPF):
- 2022 Renta: €14,000.
- 2023 Renta: €15,000.
- 2024 and 2025 Renta: €15,876.
For 2025, the second-payer amount is still €1,500: Royal Decree-law 9/2024 raised it to €2,500, but it was not validated by Congress. According to the AEAT, €2,500 applies only to amounts accrued from 1 to 22.01.2025. The €1,600 and €1,000 limits in the list did not change in those years.
Maternity and family deductions also need a return. The maternity deduction and the large family or disability deductions are paid even if your tax is 0. If you did not receive the monthly advance (Modelo 140 or 143), or received less than you were owed, the difference only comes by filing that year's Renta: maternity deduction, large family and disability.
Until when, by our calculation (4 years from the end of each filing period, arts. 66 and 67 of the General Tax Law):
- 2022 Renta: until 30.06.2027.
- 2023 Renta: until 01.07.2028.
- 2024 Renta: until 30.06.2029.
- 2025 Renta: until 30.06.2030.
If it is a refund, there is no surcharge. If you were not required to file, in principle there is no fine for filing late either, although we have not found an official AEAT position on this case.
Before you claim: check your situation
- Were you a tax resident that year? Each year counts separately: in general, if you spent more than 183 days of the year in Spain. If you arrived in 2022 after early July, you were most likely not a resident that year.
- Did you have income outside Spain from 2022 to 2025? For example, a FOP in Ukraine, a rental or remote work. That year's return must include it and may come out to pay: if the answer is yes or you are not sure, first ask for an analysis.
- Did anyone in the family receive the child support supplement of the minimum living income? Since 2023 those months do not count for maternity, with an exception for those who had both in 2022.
- Have you already received advances under Modelo 140 or 143? They are subtracted from that year's deduction. If you received them and did not file the Renta, review your case first.
- Did you file the Renta for that year? Yes: that return is corrected. No: it is filed late.
Roughly how much. What was withheld according to your withholding certificates for that year, minus the tax for the year, plus the maternity or family deductions you did not receive in advance. Example (our calculation): in 2024 you had two short contracts, of €3,000 and €2,000, with 2% withheld, that is €60 and €40. They add up to €5,000: you were not required to file, because you do not reach €15,876. You are also below the personal minimum of €5,550 (art. 57 LIRPF), so the tax comes to 0 and you get €100 back. This is a rough figure: the exact amount is known when you file the return.
Help to do it
- Free estimate: the calculator of how much the tax office may refund you estimates maternity and family deductions for 2022 to 2025. It does not work out withholding.
- Step-by-step guide «I was not required to file, but tax was withheld» (now available on this page). To file your first return, use this card's guide «Your first Renta as a foreign resident».
- Full help. We review your situation from 2022 to 2025: withholding, family deductions and foreign pensions. We work out an approximate amount and prepare a step-by-step instruction with screenshots for your case, with your figures. While you file, we support you by online chat. You file yourself: we never ask for your Cl@ve, electronic certificate, reference number or passwords. We cannot promise that there will be a refund or how much: it depends on your case and on the AEAT, and the review may show there is nothing to recover or that tax is due. Message @spain_asesor: we send you the price and the terms privately before any payment.
All the money the tax office may owe you for 2022 to 2025: How to claim a tax refund from previous years in Spain.
Documents
- NIE or TIE and a way to identify yourself: Cl@ve Móvil, an electronic certificate or a reference number.
- IBAN of your account, for the refund or to direct-debit the payment.
- Proof of income from outside Spain: payslips, a pension certificate or statements, with amounts and country.
- Proof of tax paid outside Spain, if you claim the international double taxation deduction.
- Invoices and payments for the deductions you apply, for example rent, health costs or childcare.
Indicative list: it depends on your income and deductions; check it on the AEAT website.
Doubtful cases
- First year. There is no part-year rule: the tax period is the calendar year (art. 12 LIRPF). If you spend more than 183 days in Spain that year, you are a resident for the whole year and you also declare what you earned before moving. Tax paid abroad may give you the international double taxation deduction (art. 80 LIRPF).
- Temporary protection. On its own it does not exempt you from the Renta. Binding ruling V0442-23 of the DGT (27.02.2023) deals with a self-employed Ukrainian who came to Spain in March 2022 with his family (the ruling does not mention temporary protection): it applies the general 183-day rule and cites no exception for the war.
- Resident in two countries. If another country also treats you as a resident, the treaty to avoid double taxation between the two decides. This is a case for an adviser.
- The €400 a month aid of RD 673/2022 (Ukrainians under temporary protection). It is not confirmed that it is exempt from IRPF and we have not found a DGT ruling on it. If you received it, ask an adviser before assuming it is not taxed.
- A business in Ukraine (FOP, single tax). We have not found a DGT ruling saying whether that tax counts as tax paid abroad for the double taxation deduction. It is a grey area and the AEAT might not accept it. It is another case for an adviser.
- Past years not filed. The limit was not the same every year: the reduced limit was €14,000 in 2022 and €15,000 in 2023, and since 2024 it is €15,876. If you file on your own before the AEAT contacts you and the result is to pay, there is a surcharge (art. 27 LGT, the General Tax Law): 1% plus 1% for each full month of delay. After 12 months it is 15% plus late-payment interest. If the result is not to pay, there is no surcharge, but there may be a fixed fine (art. 198 LGT): €100 if you file on your own with no prior notice, €200 otherwise. The Administration's right to assess the tax expires after 4 years (art. 66 LGT). How to file past years step by step: Renta not filed: surcharges and how to regularise.
If you live in the Comunitat Valenciana. There are regional deductions of its own, for example for rent on your main home, health costs, sport and childcare. You apply them yourself in the return and they do not always show up in the borrador (the draft return the AEAT prepares): check they are there and add any that are missing. Official AEAT list. Detail: Valencian regional deductions.
State rent deduction of Royal Decree-law 26/2026: repealed. Royal Decree-law 29/2026 provides another 10% deduction, not yet validated (see the note above). Royal Decree-law 26/2026 provided for a state deduction for rent on your main home of 10% of what you pay, but Congress repealed it on 2 October 2026 (BOE-A-2026-20526) and that deduction does not apply. More: news on the repealed deduction.
Steps
- Check that you are a tax resident that year and whether you pass a limit. You need a NIE: if you do not have one yet, see how to apply for the NIE.
- Get a way to identify yourself: Cl@ve Móvil, an electronic certificate or a reference number. How: Cl@ve and electronic certificate. For the reference number the AEAT will ask for your NIF or NIE, details of your ID document and, if you did not file the Renta last year, an IBAN (or box 0505 of last year's Renta, if you filed it) (AEAT requirements).
- Open Renta WEB and the borrador. The AEAT prepares it with data that third parties report to it; you can change it and add data.
- Add what is missing: income from outside Spain, the tax you paid abroad if you claim the international double taxation deduction and, if you live in the Comunitat Valenciana, your regional deductions.
- Check the result. If you get a refund, give your IBAN. If you owe tax, you can direct-debit the payment or pay another way; without direct debit you can only file online.
- File within the deadline. In 2026 it ran from 8 April to 30 June, with direct debit until 25 June. The AEAT will announce the Renta 2026 dates: roughly April to June 2027.
- If you need help, the AEAT offers a virtual assistant, an information phone line (Monday to Friday, 9 to 19) and appointments. In 2026 phone assistance by appointment («Le llamamos»: the AEAT calls you) started on 6 May and in-person help on 1 June. More: help services for the campaign.
Official source: art. 96 LIRPF, BOE and AEAT, Do I have to file?.
Informational only; check the official source and a professional for your specific case. Campaign figures checked on 1 October 2026.
